Skip to content
Study Hall
Lesson 5 of 9Partnerships and Corporations
Unit 3 · Lesson 5 of 9

Corporations and Classes of Shares

A corporation is a separate legal person owned by shareholders whose risk is limited to what they invested, and it raises capital by issuing common and preferred shares whose rights are set out in its articles.

7 min read1 quick check9 practice questionsAsk AI about this →

Key things to remember

  1. 1A corporation is a separate legal entity with limited liability for shareholders, continuous life and transferable shares.
  2. 2Public corporations trade on a stock exchange and report under IFRS; private corporations may use ASPE; not-for-profit corporations have no shareholders.
  3. 3Shareholders elect the board of directors; the board appoints officers and is the only body that declares dividends.
  4. 4Preferred shares have priority for dividends and on liquidation but usually no vote; cumulative preferred builds dividends in arrears.
  5. 5Authorized is the maximum allowed; issued is what has been sold; outstanding is what shareholders still hold.
  6. 6CBCA and OBCA shares have no par value, so the whole amount received is credited to the share account.

Imagine a sole proprietor who runs an outdoor-gear store. Business is good, and she wants to open three more stores, which will cost far more than she has. Banks will lend only so much. She could take on partners, but every partner would be personally liable for the debts of the whole business, and the partnership would end whenever a partner left. The usual answer is to incorporate. A corporation can sell small pieces of ownership, called shares, to many investors at once. Each investor risks only the money they put in, and the business keeps going no matter who buys or sells those shares. That is why almost every large business in Canada is a corporation, and why the accounting for owners' equity changes so much once a business incorporates.

What makes a corporation different

  • Separate legal entity. A corporation is a legal person in its own right. It owns property, signs contracts, borrows money, pays tax, and can sue or be sued in its own name. The shareholders own the corporation; they do not own its assets directly.
  • Limited liability. If the corporation fails, a shareholder can lose what they paid for their shares, but creditors cannot take the shareholder's house or savings. (Lenders to small private corporations often ask the owners to sign a personal guarantee, which removes this protection for that one loan.)
  • Continuous life. The corporation does not end when a shareholder dies or sells. It continues until it is dissolved.
  • Transferable ownership. Shareholders can usually sell their shares without the corporation's permission (public companies) or with the approval set out in the articles (most private companies).
  • Easier to raise large amounts of capital. Because risk is limited and shares are easy to transfer, many investors are willing to buy in.
  • Separation of ownership and management. Shareholders elect a board of directors, and the board hires managers. An owner does not have to work in the business.
  • More regulation and cost. Incorporating costs money, and corporations must file annual returns, keep minute books and records, and (if public) publish audited financial statements.
The double taxation idea
A corporation pays income tax on its own profit. When it later pays part of the after-tax profit to shareholders as dividends, the shareholders report those dividends as personal income, so the same profit is taxed twice. In Canada the dividend tax credit reduces the personal tax on dividends to offset much of this, but the idea that corporate profit is taxed at two levels is a key difference from a proprietorship or partnership, where the business itself pays no income tax and the owners simply pay personal tax on their share of the profit.

Public, private and not-for-profit corporations

Shareholdersown the shares; vote at theannual meetingelectBoard of directorssets policy, declaresdividends, hires theofficersappointOfficersthe CEO, CFO and managersrun daily operationsrunThe corporationa separate legal entity:owns property, signscontracts, pays its ownincome tax, continues whenowners changeLimited liabilityShareholders can lose only what they paid for theirshares; creditors cannot take their personal assets.Public corporationShares trade on a stock exchange such as the TSX;many shareholders. Must file audited IFRS statementswith securities regulators (the OSC in Ontario).Private corporationShares are not sold to the public; a fewshareholders, often a family or the founders. Usuallyreports under ASPE.Not-for-profit corporationNo shareholders and no dividends; exists for asocial, charitable or community purpose (charities,hospitals, sports clubs). Any surplus goes back intothe mission.
Fig 1Corporations split into for-profit (public or private) and not-for-profit, and can be incorporated federally or provincially.
FeaturePublic corporationPrivate (privately held) corporationNot-for-profit corporation
Who owns itMany shareholders; anyone can buy sharesA small group, often a family or foundersNo shareholders; run by members and a board
Shares tradedOn a stock exchange such as the Toronto Stock Exchange (TSX)Not traded publicly; transfers usually restricted by the articlesNo shares at all
ReportingMust publish audited financial statements; uses IFRS in CanadaStatements go to owners, lenders and the CRA; may use ASPEReports to members, donors and funders; may use ASNPO
Purpose of profitEarn a return for shareholdersEarn a return for the ownersAny surplus is put back into the organization's purpose
ExamplesA large Canadian bank or railwayA family-owned bakery chainA community sports association or a registered charity
IFRS: International Financial Reporting Standards. ASPE: Accounting Standards for Private Enterprises. ASNPO: Accounting Standards for Not-for-Profit Organizations.

A business can incorporate federally under the Canada Business Corporations Act (CBCA) or provincially, for example under Ontario's Business Corporations Act (OBCA). Federal incorporation protects the corporate name across Canada and suits a business planning to operate in several provinces, although it must still register in each province where it carries on business. Provincial incorporation is usually simpler and cheaper for a business that will operate mainly in one province. Either way, the founders file articles of incorporation, which state the corporation's name, the classes of shares and the maximum number of each class it may issue, and any rights and restrictions attached to them. The name must end in a legal element such as Limited, Ltd., Incorporated, Inc., Corporation or Corp., which warns everyone dealing with it that the owners' liability is limited. Governments also create Crown corporations (Canada Post is a federal one) to deliver public services on a business footing.
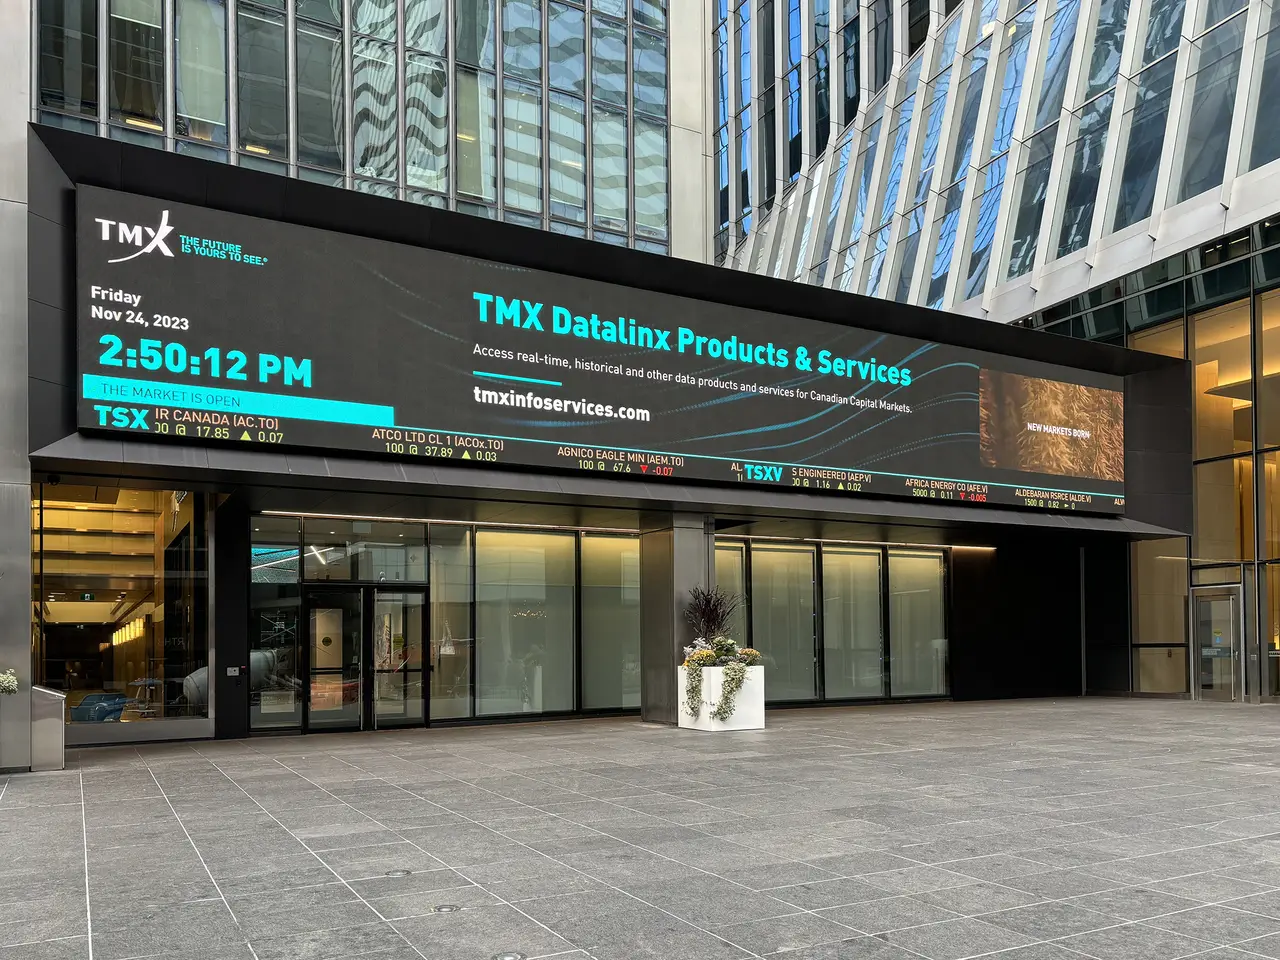
The front of the TMX Market Centre in Toronto, with a large screen showing the time, a TSX logo, the words The market is open and a ticker of share prices.
PhotoThe TMX Market Centre in Toronto, home of the Toronto Stock Exchange. The ticker shows shares of public corporations changing hands, something a private corporation's shares never do.Canmenwalker, CC BY 4.0, via Wikimedia Commons

Shareholders, directors and officers

  1. Shareholders own the corporation. Holders of voting shares elect the board of directors and vote on major changes (such as amending the articles or selling the whole business) at the annual meeting, usually one vote per voting share. A shareholder who cannot attend can vote by proxy.
  2. The board of directors oversees the corporation on the shareholders' behalf. It sets broad policy, appoints the officers, and is the only body that can declare a dividend.
  3. Officers (the president or chief executive officer, chief financial officer, and so on) run the business day to day and report to the board.
VideoIntroduces shareholders' equity and corporate governance, the relationship between the shareholders who own a corporation, the directors they elect and the officers who manage it.Watch on YouTube

Common and preferred shares

Common SharesPreferred SharesVoting rightsyesusually noneDividendsvariable, declared at board's discretionfixed rate, paid firstClaim priority (liquidation)paid lastpaid before common shareholdersShareholders' EquityShare Capital (common + preferred)Retained EarningsShare capital = what shareholders paid in; retained earnings = accumulated profit not paid out as dividends.
Fig 2Common shareholders carry the most risk and the most upside; preferred shareholders accept a fixed dividend in exchange for being paid first.
RightCommon sharesPreferred shares
VotingUsually one vote per shareUsually no vote (unless dividends go unpaid or the articles say otherwise)
DividendsWhatever the board declares after preferred is paid; no fixed amountA stated amount per share each year (for example $4 per share), paid before any common dividend
On liquidationReceive whatever is left after creditors and preferred shareholdersPaid back before common shareholders, after creditors
Risk and rewardHighest risk; share in all growth through rising dividends and share priceLower risk; return is mostly capped at the fixed dividend
Every corporation must have at least one class of shares with voting rights; most call it common shares.
  • Cumulative preferred: any year's preferred dividend that is not declared accumulates as dividends in arrears, and all arrears plus the current year must be paid before common shareholders receive anything.
  • Non-cumulative preferred: a missed year is lost forever. Preferred shareholders only have a claim to the current year's dividend.
  • Participating preferred: after preferred and common have each received a set amount, preferred shareholders share in any extra dividend. Most preferred shares are non-participating.
  • Convertible preferred: the holder may exchange each preferred share for a set number of common shares.
  • Redeemable (callable) preferred: the corporation may buy the shares back at a stated price. (Retractable shares give the holder the right to demand repayment.)

Three share counts matter. Authorized shares are the maximum the articles allow; CBCA and OBCA corporations may authorize an unlimited number. Issued shares are the shares the corporation has actually sold or exchanged since it was formed. Outstanding shares are issued shares still held by shareholders. In Canada, shares a corporation buys back are normally cancelled, so issued and outstanding are usually the same number. Finally, Canadian corporations under the CBCA and OBCA issue shares with no par value: a share has no printed face amount, so the full amount received is credited to the share account.

Quick checkTry it before you read on
1
Maple Ridge Outfitters Ltd. has 10,000 preferred shares authorized and has sold 2,000 of them. It has never repurchased any. How many preferred shares are outstanding?

Worked examples

Reveal one step at a time and try to beat it to the next line.

Example 1
Maple Ridge Outfitters Ltd.'s articles authorize "unlimited common shares, and 10,000 $4 cumulative, non-participating, redeemable preferred shares." Explain what each term tells an investor about the preferred shares.
Example 2
By Dec. 31, 2026, Maple Ridge has issued 50,000 common shares and repurchased and cancelled 3,000 of them. It has issued 2,000 of its 10,000 authorized preferred shares. State the authorized, issued and outstanding numbers for each class.
Example 3
Classify each organization as a public corporation, private corporation or not-for-profit corporation: (a) a hockey association that runs minor-league programs and puts any surplus into ice time and equipment; (b) a family-owned chain of four hardware stores whose three shareholders are siblings; (c) a mining company whose shares trade on the TSX.

Where marks get lost

  • Saying shareholders own the corporation's assets. The corporation owns its assets; shareholders own shares in the corporation.
  • Mixing up authorized and outstanding shares, for example using the 10,000 authorized preferred shares to calculate a dividend when only 2,000 are outstanding.
  • Thinking preferred shareholders are guaranteed a dividend every year. No shareholder is owed a dividend until the board declares one; cumulative only means missed amounts must be caught up before common gets paid.
  • Believing directors and shareholders are the same people. They can overlap in a small private company, but they are different roles: shareholders elect the directors.
  • Using par value or "contributed surplus in excess of par" for a Canadian share issue. CBCA and OBCA shares have no par value.

Flashcards 8

Limited liability
Separate legal entity
Public vs private corporation
Board of directors
+ 4 more

Practice

1
Which feature of a corporation most directly explains why investors who will never work in the business are willing to buy its shares?
2
Match each preferred-share feature to its meaning.
Cumulative
Participating
Convertible
Redeemable
3
A corporation's articles authorize 50,000 preferred shares. It has issued 18,000 and has repurchased and cancelled 3,000 of those. How many preferred shares are outstanding?
shares
4
Who has the legal authority to declare a dividend?
5
Put these in order of who is paid first if a corporation is liquidated (dissolved and its assets sold).
  1. 1Preferred shareholders
  2. 2Creditors
  3. 3Common shareholders
6
What is the name of the founding document a business files to incorporate, which lists its share classes and how many of each it may issue?
7
A not-for-profit corporation differs from a private corporation mainly because it...
8
A shareholder owns 1,000 of a public corporation's 2,000,000 voting common shares. Which right does this shareholder have?
9
Canadian corporations incorporated under the CBCA or OBCA issue shares with no ____ value. Fill in the blank.

Spot a mistake on this page? Let us know